In this post
- Step 1: Document the damage before anyone touches the roof
- Step 2: Know your policy before you file
- Step 3: File the claim and get a roofer's inspection
- Step 4: Meet the adjuster
- Step 5: Read the estimate and the first check
- Step 6: Get the work done and close the claim
- Get the roof checked before you file
- Common questions
A hail damage roof claim in Oklahoma City follows a set path: document the damage, report it, meet the adjuster, read the estimate, then get the work done before the policy's deadline so the held back money is released.
Most of the trouble we see comes from skipped steps, not denied claims. McRay has taken on 203 roofing jobs in and around Oklahoma City, and a large share of them started the same way, with a homeowner standing in the yard after a storm wondering what to do first. Here is the order that works.
Step 1: Document the damage before anyone touches the roof
The Oklahoma Insurance Department tells homeowners to take plenty of photos or video of the damage, cover leaks and holes with temporary repairs, and save every receipt. It also says not to make permanent repairs until your insurer has inspected the property.
From the ground, photograph the things you can reach safely:
- Dents in gutters, downspouts and the soft metal caps on roof vents
- Granules piled at the bottom of downspouts
- Spatter marks on fences, the A/C unit and painted trim
- Water stains on ceilings, with the date
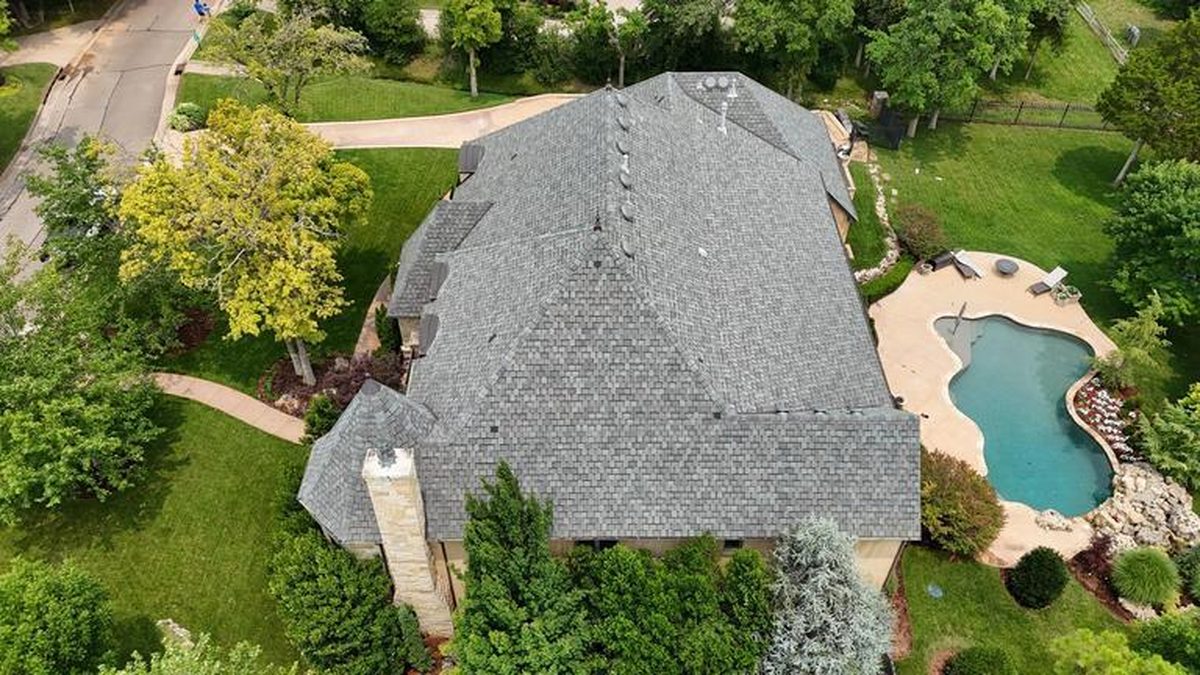
Those soft metal dents matter. When our crews walk an OKC roof after a hail event, the dented vent caps and gutters are often what convinces an adjuster that bruised shingles came from this storm and not from age. Leave the climbing to someone with fall protection. A drone or a roofer with a harness can get the close shots you need, like the circled hits in the photo above.
Step 2: Know your policy before you file
Pull your declarations page and find three things: your deductible, whether there is a separate wind and hail deductible, and whether the dwelling is covered at replacement cost or actual cash value.
The OID's storm FAQ notes that many companies now carry an optional deductible that applies only to wind or hail losses. If that deductible is a percentage of your dwelling coverage, it can be much larger than the flat deductible you remember signing up for.
The difference between the two ways a roof can be paid out is the part people miss most often:
| Replacement cost value (RCV) | Actual cash value (ACV) | |
|---|---|---|
| What it pays for | The cost to replace the roof with like materials | The replacement cost minus depreciation |
| First check | Usually the depreciated amount, minus your deductible | The depreciated amount, minus your deductible |
| Held back money | Released after the work is done, within the policy's time limit | Generally not paid; depreciation is the deduction |
| Older roof | Still paid to replace, once completed | Payout can be far below the cost of a new roof |
The OID FAQ also lists the cost of meeting updated building codes as an item homeowners policies usually limit. If your roof needs work to meet current code, ask your agent whether you carry ordinance or law coverage.
Step 3: File the claim and get a roofer's inspection
Report the claim through your carrier's app, website or phone line and write down the claim number. The state also asks people to report storm damage at damage.ok.gov, according to the same OID release.
Have a local roofer you trust inspect the roof before the adjuster arrives, or at least before you accept a number. You want someone who knows how central Oklahoma hail marks a shingle, and who will tell you plainly if the roof is fine. Some roofs we climb after a storm simply do not have enough damage to be worth a claim, and you should hear that before you file. Our roof inspection is free for that reason.
Check the roofer's state registration with the Construction Industries Board license lookup before you sign anything. Our older post on telling storm damage from normal wear shows what an honest inspection looks for.
Step 4: Meet the adjuster
Be home for the adjuster's visit and, if you can, have your roofer there too. On the OKC roofs we meet adjusters on, most mark a test area on each slope and count hits inside it. Your roofer can point out damage on the ridge, valleys and flashing that is easy to miss from one test square.
Things worth asking on the roof:
- Which slopes are being replaced, and which are not?
- Are the gutters, vents, skylights and other metal included?
- Is depreciation being held back, and how much?
If you feel the adjuster is not addressing your questions, the OID's after the disaster guide suggests asking to speak with someone at a management level.
Step 5: Read the estimate and the first check
The estimate is a long list of line items. Compare it with your roofer's scope. On OKC jobs, the items we most often find missing are starter shingles, drip edge, ridge cap, valley metal, pipe jacks and the extra labor for a steep or two story roof. When something is missing, the roofer sends the insurer a supplement with photos and measurements. That is normal and should be done openly, with you copied.
The first check usually covers the depreciated value minus your deductible. If you have a mortgage, expect the lender's name on the check too. The OID notes that some mortgage servicers require two signatures because the lender has a financial interest in the home being repaired.
The deductible is yours to pay
The OID warns homeowners to avoid any contractor who offers to waive the deductible or promises a rebate, and says plainly that it is against the law. A roofer who offers to "take care of it" is putting your claim at risk along with their own.
Your right to cancel if the claim is denied
Under the Oklahoma Roofing Contractor Registration Act (59 O.S. 1151.21), if you sign a roofing contract that will be paid from an insurance claim, you can cancel it within 72 hours of receiving the insurer's written notice that the claim was denied in whole or in part. The contractor has to give you that notice in the contract.
Step 6: Get the work done and close the claim
The clock starts on the date of loss, not the date you were paid. The OID says replacement cost policies require the work to be completed within six months of the date of loss to receive the withheld payments. Book your crew early; after a big OKC hail day, every roofer's schedule fills fast.
Do not pay the full amount up front or sign over your settlement check, another warning in the OID guide. A sound contractor collects in stages tied to the work.
When the roof is done, your roofer sends the insurer the final invoice and photos, and the carrier releases the held back depreciation, plus any approved supplements. That is when the claim is truly finished. If you are replacing the whole roof anyway, it is worth asking about impact resistant shingles while the claim is open; we covered that in whether Class 4 shingles are worth it in Oklahoma City.
If something goes wrong along the way, the OID Consumer Assistance Division is at 800-522-0071, and the release lists the Attorney General's Consumer Protection Unit at 833-681-1895 for suspected contractor fraud.
Get the roof checked before you file
If hail came through your part of Oklahoma City, start with a free inspection so you know whether a claim makes sense. Call McRay at (405) 692-4000 or send us a message, and we will tell you what we find, including when the answer is that you do not need us. Our storm damage restoration team can walk the roof with your adjuster if you do.
Common questions
Should I call my insurance company or a roofer first after hail in Oklahoma City?
Get the roof inspected first if you are unsure there is damage, so you know whether a claim is worth filing. If damage is obvious, report it to your insurer promptly and take photos before anything is repaired.
Can a roofer pay my deductible in Oklahoma?
No. The Oklahoma Insurance Department warns homeowners to avoid contractors who offer to waive a deductible or promise a rebate, and says the practice is against the law.
How long do I have to finish repairs to get my depreciation back?
The Oklahoma Insurance Department says replacement cost policies require the work to be completed within six months of the date of loss to receive the withheld replacement cost payment. Check your own policy for its exact terms.
Can I cancel a roofing contract if my claim is denied?
Under the Oklahoma Roofing Contractor Registration Act, a homeowner who signed a contract to be paid from an insurance claim can cancel within 72 hours of receiving the insurer's written notice that the claim was denied in whole or in part.